

You can claim your UK State Pension in Germany if you have enough National Insurance contributions, for the new State Pension usually at least 10 qualifying years. The maximum pension amount for the 2026 to 2027 tax year is £241.30 a week. Because Germany belongs to the European Economic Area, your State Pension increases each year in line with the UK rate. You can claim through the International Pension Centre from four months before you reach State Pension age, and the pension can be paid into a German account, with a conversion charge of 0.39%.
Since April 6, 2026, voluntary Class 2 contributions for periods abroad have largely ended. New applicants for Class 3 must have lived in the UK for at least 10 continuous years or have at least 10 qualifying years, and voluntary contributions already paid for periods abroad generally do not count toward those 10 years. Earlier tax years remain under the previous rules.
Please note: Current Class 2 payers who meet the existing conditions can apply to switch to Class 3 before April 6, 2027, without the 10-year test. Check your National Insurance record and State Pension forecast well before that date, because voluntary contributions do not always increase your pension.
UK workplace and personal pensions can generally stay where they are when you move to Germany. Some British expats consider moving their pension pot to a qualifying recognised overseas pension scheme (QROPS). Since October 30, 2024, the 25% Overseas Transfer Charge also applies to transfers to a QROPS in the EEA or Gibraltar. The main exclusion applies if you live in the same country as the receiving scheme and stay within your overseas transfer allowance. Please note that the charge can also arise after a transfer if your circumstances change.
Whether keeping or transferring makes sense depends on costs, currency, investment options, tax in both countries and the death benefits of each scheme. We show how each option fits into your overall retirement plan; a recommendation on a specific transfer comes from a specialist we bring in where needed.
Under the UK–Germany double taxation treaty of March 30, 2010, you do not pay tax on the same income in both countries. Which country taxes a pension depends on its type:
General rule under the treaty: Taxable only in the UK (Article 17(2))
General rule under the treaty: Generally taxable only in Germany as your country of residence (Article 17(1)); taxable only in the UK if contributions were tax-relieved there for more than 15 years and the UK effectively taxes the pension (Article 17(3))
General rule under the treaty: Taxable only in the UK, unless you are resident in Germany and a German national (Article 18(2))
Lump sums and the timing of withdrawals depend on your situation. We do not provide tax advice; a tax advisor with UK and German experience from our network can assess your case.
Under the Finance Act 2026, most unused pension funds and pension death benefits count toward the estate for UK inheritance tax when death occurs on or after April 6, 2027. Estate plans built on the previous rules, under which such funds usually passed free of inheritance tax, may no longer work as intended. Transfers to a surviving spouse or civil partner are exempt where they are long-term UK residents; please note that different rules can apply if one of you does not meet that test.
Living in Germany does not take your UK pension out of UK inheritance tax. According to HMRC, the new rules cover pension schemes established in the UK regardless of where you live, while schemes established outside the UK are only in scope for long-term UK residents. Since April 6, 2025, that status applies to anyone who was UK resident for at least 10 of the previous 20 tax years, and after leaving the UK it continues for three to ten years. Germany taxes the entire inheritance when the deceased or the heir lives in Germany. There is no inheritance tax treaty between the two countries; German law allows foreign inheritance tax to be credited on application under certain conditions.
Please note: If you hold UK pension savings and have family in both countries, review your beneficiary nominations and estate plan with a tax advisor before April 2027.
Health insurance is compulsory for residents in Germany, and British citizens usually join a statutory health insurer (Krankenkasse) or a private insurer. If you draw a UK State Pension while living here, you may be entitled to UK-funded healthcare through an S1 form. Registered with a statutory German insurer, it gives you and your dependents cover on the same basis as German citizens.
Since January 1, 2021, the EU–UK Trade and Cooperation Agreement coordinates social security for new cross-border situations; according to the German liaison agency DVKA, its rules largely mirror EU coordination rules. Some German rules require prior insurance, for instance for voluntary statutory cover, and whether your UK years count depends on your history, so have this checked before you rely on it.
Switching from private back to statutory insurance is restricted, especially after 55, so your choice on arrival shapes your cover in retirement. Our page on health insurance for expats in Germany explains how we compare policies by their conditions.
Our advice follows three steps: we clarify your goals, analyze your current financial status and create an individual financial plan. For British clients we bring State Pension forecasts, UK scheme statements and German documents together in our customer portal with digital folders.
in English or German, with German letters explained in English
Cathy Matz-Townsend is an insurance broker registered under section 34d paragraph 1 GewO, independent of banks and insurers
tax advisors, lawyers, notaries and pension experts for cross-border questions
After an initial discussion, we could either continue with a full financial plan which is fee-based or provide insurance and/or investment consultations which are generally commission-based. Details are found on our contact page and in the regulatory information.
A British couple in their late fifties moved to Germany for work some years ago. One partner holds two UK pensions, the other has gaps in the National Insurance record, and a former colleague has suggested a pension transfer. We would gather the forecasts and statements and check which gaps can still be filled under the rules since April 2026, and whether paying for them would increase the pension. A tax advisor from our network clarifies the treaty and inheritance tax questions, and we review whether the health insurance will still fit in retirement.
"Matz-Townsend Finanzplanung offer everything that we, as expats, had hoped to find – experience and insight, responsive and clear communication, and sound guidance without pressure. Cathy and John have listened to our needs and smoothly helped us achieve our goals."
Prof. Dr. K.J.
"Cathy guided us through the complex health insurance system. Patiently, competently and always with our situation in mind."
Anonymous
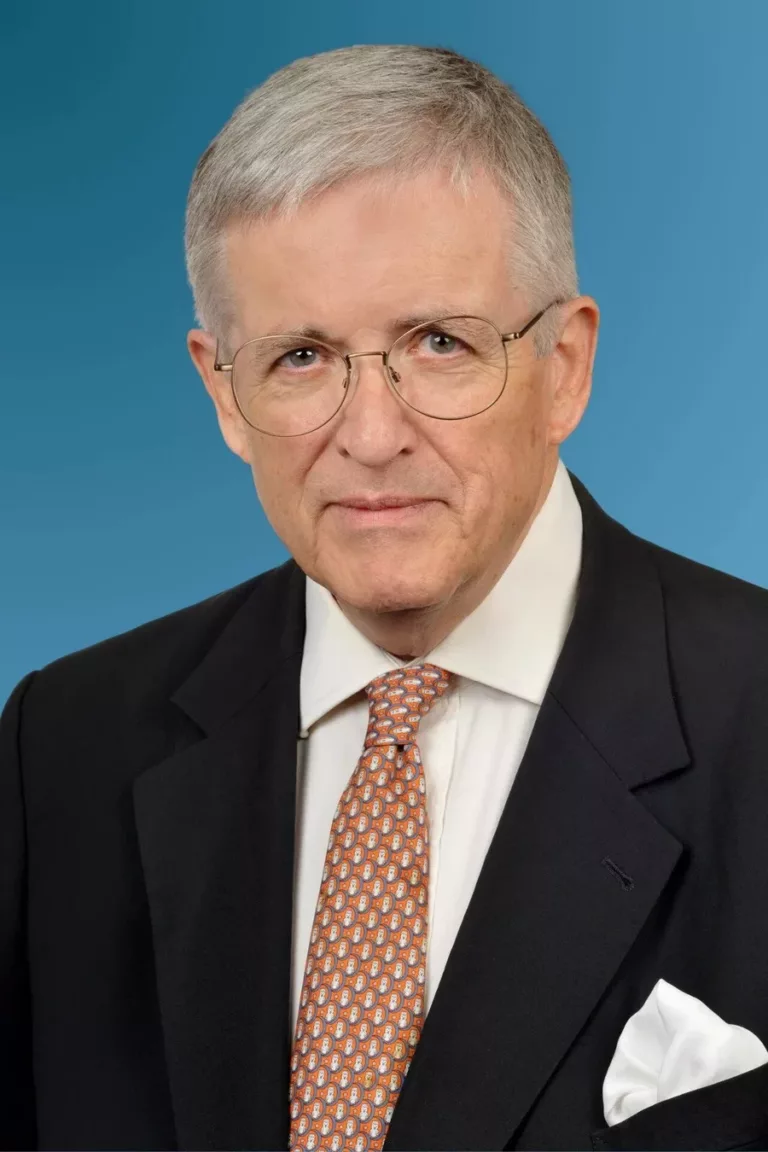
MBA B.Sc. (Econ) FCSI
Investment Fund Portfolio Adviser
John has lived in Germany since 2001 after previously residing in Great Britain, Japan and the United States. He holds a B.Sc. (Econ) from the London School of Economics, is a Fellow of the Chartered Institute for Securities and Investment (CISI) and has constructed fund portfolios for our clients since 2004.
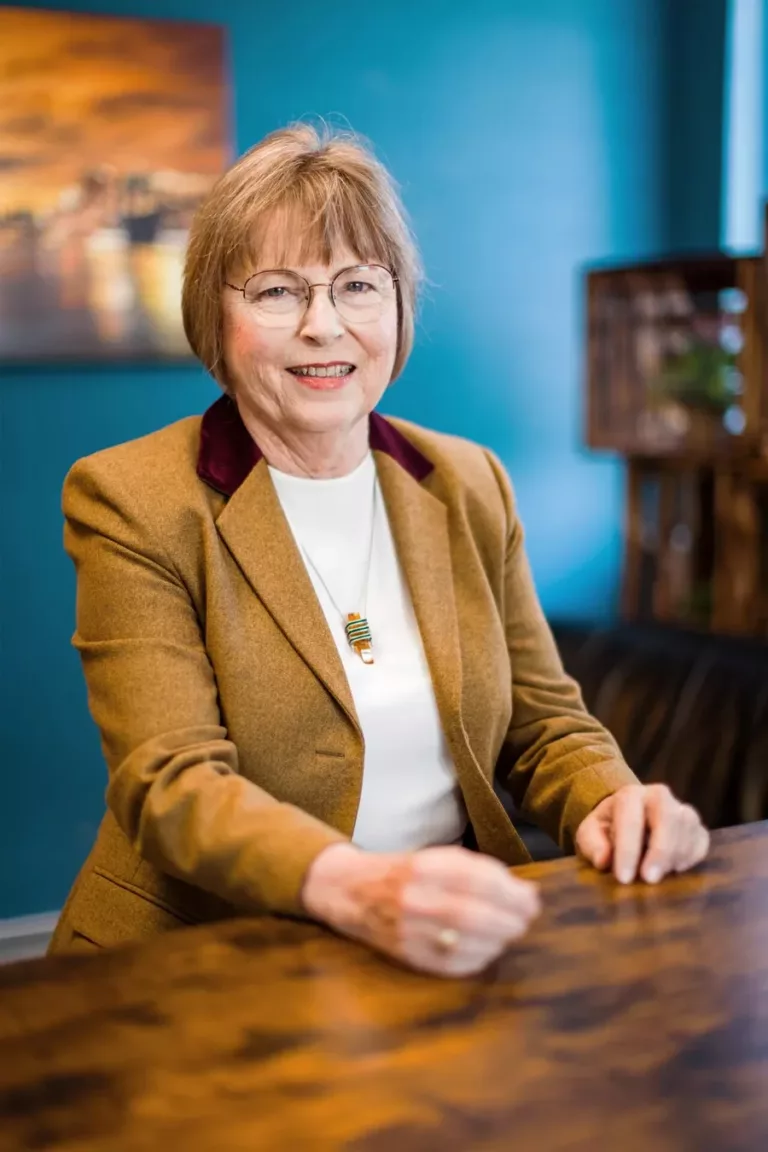
Dipl. Betriebswirtin (FH)
Insurance broker
Cathy has been a self-employed insurance broker since 1988, specializing in health insurance and long-term pension planning. She has been a certified Generational Adviser (IHK) since 2015 and a certified retirement planning advisor (GP) since March 2026.
Yes, if you have enough qualifying years on your National Insurance record, usually at least 10 for the new State Pension. Because Germany is in the EEA, the pension increases each year.
There is no general answer, because costs, tax and death benefits differ between schemes.
It is a 25% UK tax charge on transfers to a qualifying recognised overseas pension scheme (QROPS). Since October 30, 2024, it also applies to schemes in the EEA and Gibraltar unless an exclusion applies.
For deaths on or after April 6, 2027, most unused pension funds count toward the estate for UK inheritance tax. This applies to pension schemes established in the UK even if you live in Germany, and German inheritance tax may also apply.
Under the treaty, the UK State Pension is taxable only in the UK, while workplace and personal pensions are generally taxable in Germany, with exceptions such as the 15-year rule.
Employees earning below the annual income threshold are generally insured in the statutory system, and UK State Pension recipients may register an S1 form with a statutory insurer. In other cases access is limited, so get advice before you sign a policy.
Send us a short message about your UK pensions and your plans in Germany. We will take time for your questions.
Contact us nowThis page is for general information only and does not replace individual advice on insurance, investments, tax or legal matters. Information as of October 2026, without guarantee.